


I have written this newsletter the same way for a long time. News, then commentary, then links. I am retiring that ship. The last 28 days did not produce a list of unrelated stories. Instead, there was one story, told four times, in four countries, by four governments. A list would have buried that. I added the sources at the end so you can refer to them in detail and form your own opinion.
If you want to chat about anything and everything coliving.
In 28 days:
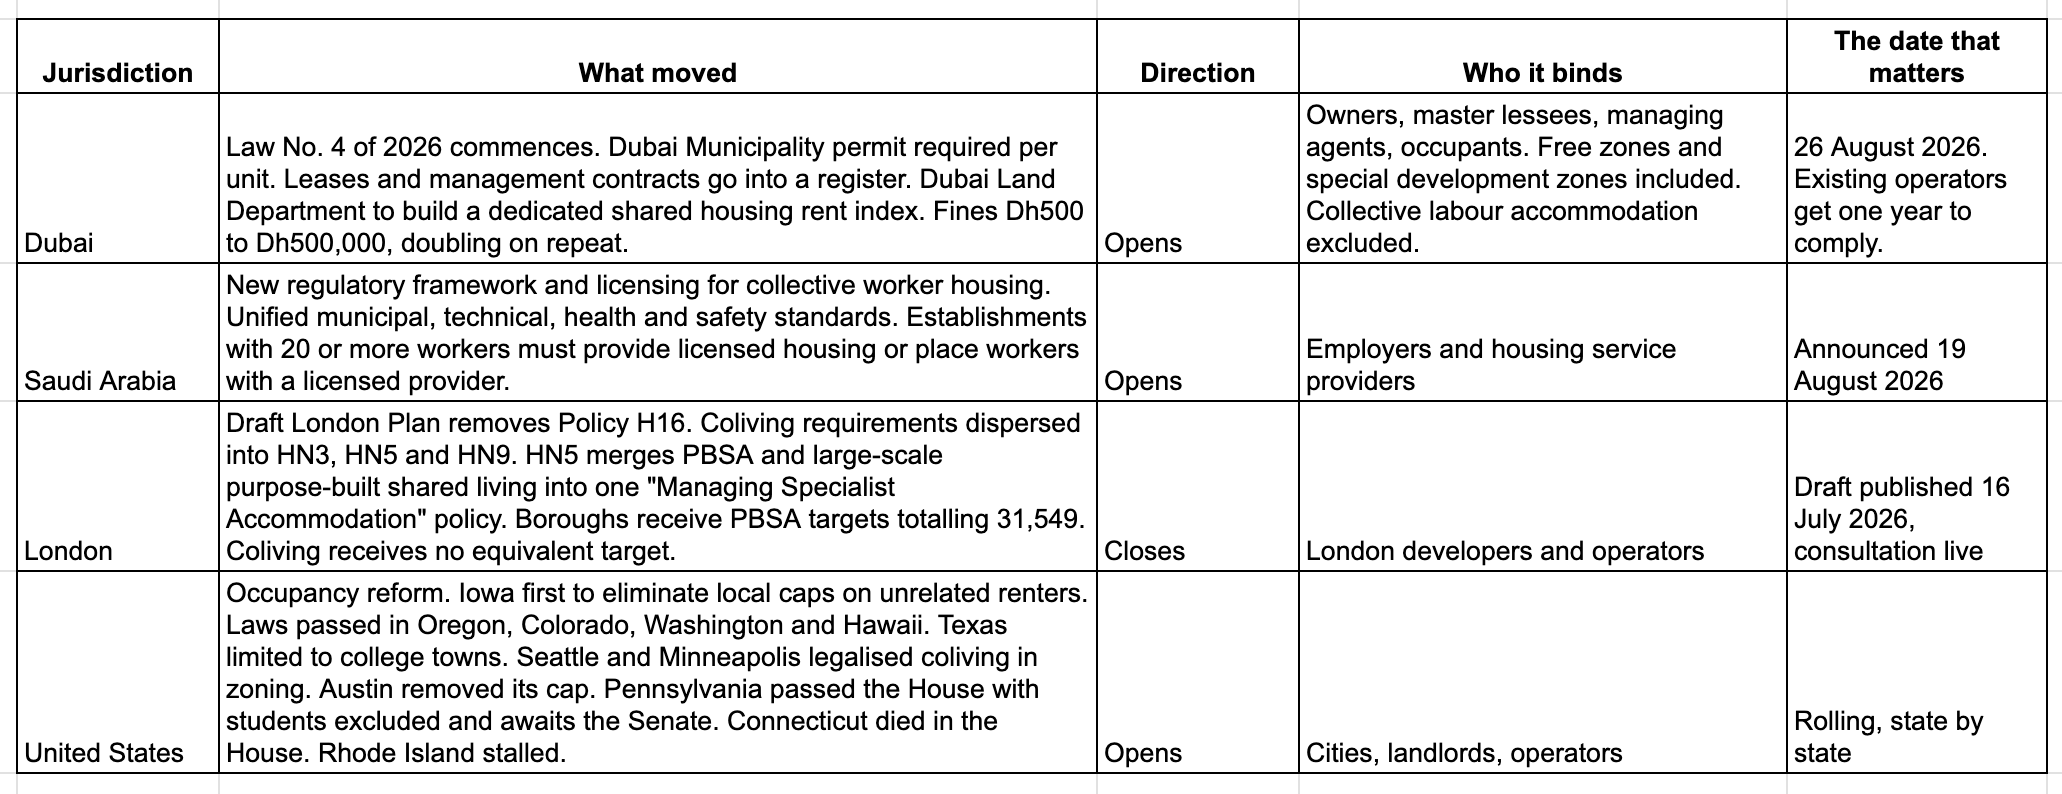
Dubai’s shared housing law reached its commencement date.
Saudi Arabia published a licensing framework for collective worker housing.
The Draft London Plan deleted coliving’s dedicated policy.
And a bloc of US states continued dismantling caps on how many unrelated people can share a home, now with a trade association behind them.
Coliving is now moving on from being just a product category to a regulated use category.
The part almost nobody is saying out loud: the regulation is moving in two opposite directions at the same time. The Gulf and the United States are creating legal space for shared living where none existed before. London is dissolving the legal space that coliving had already won. Same asset class. Opposite policy vectors in the last 28 days.
If you operate in one market, you will read the situation as good news or bad news. If you operate in several, read it as the end of the single global playbook. There isn’t one any more.
THE REGULATORY LEDGER
Dubai is the one to actually read
I ran 500 units across 17 locations in one Indian city on master leases. Master leasing works because it is fast and capital-light, and because nobody is looking too closely at the unit level. Dubai just wrote the master lessee into the law and put the contract in a government register.
That is not a crackdown. It is a formalisation, and formalisation is exactly what institutional capital has been waiting for in the Gulf. Three things now exist that did not exist before: a legal use, traceable income, and a benchmark. The Land Department building a shared housing rent index is the quiet headline of the entire month. You cannot underwrite what you cannot benchmark. From next year, you can.
The bill for that arrives as compliance overhead. A permit per unit. Contracts registered. Occupancy caps, space minimums, inspections. Operators running this on spreadsheets and WhatsApp will not survive it quietly.
When I built a coliving PMS, compliance reporting was the module nobody wanted to pay for. Everyone wanted the booking engine. In Dubai it just became the module you cannot open the doors without.
One honest caveat, because I would rather be right than early: the law creates the authority to set numeric occupancy caps, per-resident floor areas and shared facility ratios. It does not set them. Municipality permit procedures, the technical guide and the fee schedule are the documents that will actually determine whether this is affordable to comply with. Until those publish, anyone quoting you a compliance cost is guessing.
Saudi Arabia is the story our industry will ignore
And it is the largest one in this newsletter by bed count.
The Kingdom is standardising housing for workers at national scale. Licensed providers, unified standards, a mandate on every employer with 20 or more staff. That is not an adjacent market. That is the Middle East coliving archetype doing exactly what I have argued it does: upgrading and standardising blue-collar workforce housing, rather than importing a lifestyle product from Europe.
We do not cover it because it is not design-led and it does not photograph well.
If your definition of coliving cannot accommodate several million workers being moved into licensed, standardised, professionally managed shared accommodation, your definition is too small. Mine includes it.
London deleted the policy, but the policy was not the problem
The removal of H16 is being read as a downgrade. Half right.
Here are the numbers that matter more. Savills puts London coliving starts down roughly 85% from their Q4 2023 peak, with just over 16,000 consented units not yet on site as of July 2026. DFI’s own market note this month put operational coliving beds across London at around 7,000.
Read those two figures together. London has consented more than twice its entire operational stock and then not built it.
That is not a policy problem. It is a viability problem. Land price, build cost, funding cost and payment in lieu. Moving the words from H16 into HN5 does not change a single line in a development appraisal.
The detail that does matter: PBSA got borough targets totalling 31,549 units. Coliving got none. Targets pull product through a planning system. Guidance does not. If you develop in London and you only read one thing in the draft, read that asymmetry, then write to the consultation about it.
THE MONEY MOVED TWICE, AND BOTH TIMES AWAY FROM RISK
6 August. Meridia acquired a 977-unit purpose-built flex living asset in Carabanchel, Madrid, from the joint venture between Bain Capital, Momentum REIM and Episode. The building opened in April 2025, runs to more than 30,000 sqm, holds BREEAM Outstanding, and took the ASPRIMA-SIMA award for best flex living initiative this year. Episode stays on as operator. The JV has now completed and exited around 2,800 units and is building a second portfolio of more than 2,300.
19 August. DFI forward funded a 200-bed coliving scheme in Kingston upon Thames, £80m gross development value, off market, with Viewranks Estates delivering. The scheme already had full planning permission and Gateway 2 approval.
Now look at what both buyers refused to touch.
Meridia bought a building that was already open, already stabilised, already award-winning, with the operating team staying in place. DFI forward funded a scheme where entitlement and building safety approval were already banked.
Neither took planning risk. Neither took lease-up risk. One took construction risk on a fully de-risked consent.
This is the most useful signal of the month for anyone raising money. Capital has not left coliving. Capital has left the front of the curve. If your pitch asks an investor to underwrite entitlement, construction and lease-up in a single decision, you are pitching into the one segment of the market that has closed.
The Bain, Momentum and Episode cycle is the template worth copying: develop, stabilise, sell to core capital, keep the operating contract. Episode gave up the asset and kept the annuity.
I have spent enough time in Spain, as media partner at SIMA and working with operators there, to say this plainly. The Spanish flex living market has moved past the hype stage into repeatable transactions with a proven exit. That is rarer than the headlines suggest, and it is why Spain is currently the most instructive market in Europe.
One number: 16,000. London coliving units with planning consent that have not started on site, as of July 2026. Source: Savills.
THE HABYT TELL
On 1 August, Habyt opened a 319-unit aparthotel in Vienna’s Nordbahnviertel, delivered by Strabag Real Estate. It is among the largest serviced apartment openings in Austria this year.
Now go and look at the destinations menu on habyt.com. Berlin. Madrid. Vienna. Lisbon and Milan marked coming soon.
The sequence behind that menu: Asia Pacific operations sold to Mitsubishi Estate in April. French, Portuguese and Spanish coliving portfolios sold to three local operators in May. Atipico launched as a hotel brand. Leaze launched as a separate asset-light coliving brand. Then Vienna in August.
The lazy version of this story is that coliving’s biggest operator gave up on coliving. That is not what happened, and Leaze exists to prove it.
What actually happened is a company deciding that three different products should stop sharing one P&L. Aparthotels under Habyt. Hotels under Atipico. Asset-light coliving under Leaze. Three products, three risk profiles, three balance sheet treatments.
That is a sophisticated answer to a problem I have watched kill operators for a decade. Mixed stay lengths, mixed service intensity and mixed capital intensity inside one brand produce blended metrics that mean nothing. You cannot run a portfolio on a blended RevPAB when a third of it is one-night stays and a third is twelve-month tenancies. The board sees one number. The number is fiction. Decisions get made on it anyway.
The tell here is not the retreat. It is the unbundling. Expect more operators to split the brand rather than the footprint.
THE PADSPLIT ARITHMETIC
Standing disclosure first, because consistency matters more than access. PadSplit is house sharing, not coliving. I have written that before and I am not moving on it. Rooms in single-family homes with no community operating layer is a different business from purpose-built shared living. Both are legitimate. They are not the same asset class and they should not share a benchmark.
With that said, PadSplit had the busiest month of any operator in the sector.
5 August. HostGuard launched, underwritten by EmpoweredRE. It covers property damage, evictions, general liability, and occupancy-related zoning actions. It applies to every new member and every existing member who moves to a new property. Atticus LeBlanc said openly that it is modelled on Airbnb’s AirCover.
11 August. Inc. 5000 for the fifth consecutive year. No. 996 overall, 350% three-year revenue growth, No. 19 among US real estate companies.
Now the arithmetic nobody has run publicly.
HostGuard is funded by a 2.25% increase in member transaction fees. PadSplit puts that at roughly $4 a week per user. Members are the residents.
So a product designed to reduce landlord risk is paid for by tenants, at around $208 a year each, with no opt-out, whether or not a claim is ever made on their home.
I can argue this both ways, and both arguments are real.
For: if HostGuard pulls supply off the sidelines, residents get more choice, faster approvals and a higher acceptance rate. LeBlanc explicitly expects rejection rates to fall. A resident approved for $4 a week is better off than a resident rejected for free. Against a median tenant income around $30,000, access beats savings almost every time.
Against: PadSplit’s residents are among the most cost-constrained renters in the United States. Charging them a mandatory fee to insure their landlord’s downside is a transfer of risk cost from the strongest party in the transaction to the weakest.
My position: the product is right and the funding mechanism is wrong. Fund it host-side and let hosts price it into the room rate if they need to. The money lands in the same place. The optics do not.
And optics are not a small thing here, because PadSplit is currently the most visible private-sector voice arguing for occupancy reform in US state legislatures. The first time a legislator holds up “$208 a year, charged to the tenant, for the landlord’s insurance” in a committee hearing, that sentence will do more damage than the fee ever earned.
SINGAPORE PUT THE STATE’S NAME ON IT
20 August. Singapore’s SG Youth Plan launched a pilot coliving programme for adults aged 21 to 35. Two operators. Just over 100 discounted rooms. Rents from SGD 1,800. Leases as short as one month.
The scale is nothing. Coliwoo alone runs 3,568 rooms at 97% occupancy as of 31 March. A hundred rooms is a rounding error.
The signal is enormous.
A government has told its own young citizens that renting a room in a professionally operated shared building is a legitimate stage of life rather than a failure to buy. In a country organised around getting a flat and getting married in that order, that is a real shift in what the state is willing to endorse.
Commentators moved fast to note that the pilot is privately funded, small, and mostly reachable by higher-income young professionals delaying marriage. All true. Also true of the first PBSA scheme in every market that now counts its beds in the tens of thousands.
Watch the definitions next. Singapore already has the most explicit coliving rules anywhere: 90-day minimum stays, occupancy caps, service apartment classification. Once the state names a housing format in a national youth plan, it acquires a reason to revisit every one of those rules. That is where this gets interesting.
CALLED IT, MISSED IT
New section, and it stays. Editorial credibility is the only asset this newsletter has, so I am going to keep score in public.
Called it. I argued that Dubai’s law would institutionalise coliving rather than suppress it, and that the rent index was the part that mattered rather than the fines. The index is confirmed and the Land Department is building it.
Called it. The regional archetype thesis held up under a heavy news month. India, the Gulf, Southeast Asia, Australia and the US, and Europe are solving five different problems with the same physical product. Nothing in the last 28 days contradicted that.
Missed it. I have badly underweighted US state legislatures. I have spent two years writing about capital and planning while Iowa, Oregon, Colorado, Washington, Hawaii and Texas quietly deleted or loosened caps on unrelated occupancy, and a National Co-Living Association formed to push for more. That is a structural change to the largest housing market on earth and I have been treating it as a footnote.
Missed it. I described London’s consent pipeline as healthy in an earlier edition. Savills has now put starts down about 85% from peak. Consents are not a pipeline. Starts are a pipeline. I should have drawn that line much earlier, and if you made a land decision partly on my read, that one is on me.
WHAT I WOULD DO ON MONDAY
If you operate in Dubai. The one-year clock starts on 26 August, not when you get to it. Audit every unit against occupancy and space standards now, before Municipality inspection scheduling gets congested and before every other operator wakes up in month eleven. If your lease and management contracts do not sit in a system that can produce a registered contract on demand, that is your first purchase this quarter, not your last.
If you develop in London. Stop optimising the consent and start optimising the appraisal. There are 16,000 consented units nobody has built, so consent is no longer a differentiator. Then respond to the Draft London Plan consultation. HN5 folding coliving in with PBSA while only PBSA receives borough targets is the single most consequential line in the document, and it is still a draft.
If you operate in the US. Find out what the National Co-Living Association is asking for in your state, and get in the room. Occupancy caps are being rewritten one legislature at a time, and the operators present when it happens will get a version they can actually build to.
If you operate in India. Dubai and Riyadh are your leading indicator, not London. Every Indian city runs on informal shared housing regulated as nothing in particular, while coliving is still routinely conflated with PGs and BTR is still marketed as coliving. That confusion is not harmless. It means that when regulation arrives here, and it will, it gets drafted by people who have never operated a bed, using definitions the industry never bothered to fix. Fix the definitions now, while it is still cheap.
If you are raising. Build the story around the stabilised handover, not the ground-up vision. Show the operating contract you keep after the exit. That is the shape capital bought twice this month.
THE WATCHLIST
26 August. Dubai Law No. 4 of 2026 in force. The one-year compliance window opens.
Next. Dubai Municipality permit procedures and technical guide, plus the Executive Council fee schedule. Until these publish, the real cost of compliance cannot be priced.
11 September. Urban Living News webinar on the future of coliving.
Autumn. Draft London Plan consultation responses. This is the window where the PBSA and coliving target asymmetry can still be argued.
End of November. Pennsylvania’s shared housing bill needs Senate action before the session closes.
Ongoing. The first published Dubai Land Department shared housing rent index. When it lands, it will be the most important number the Gulf coliving market has ever had.
The operators who come out of this well will not be the ones with the best community programming. They will be the ones who can produce a registered contract, a permit, and a clean occupancy record on the day someone asks.
That is a boring sentence. It is also the whole game now.
See you next month.
Mayank
Everything Coliving. 12 years in the industry, 100+ coliving and proptech brands, operators in 14+ countries. If something in here is wrong, tell me and I will correct it in the next edition with your name on it.
SOURCES
Everything in this edition is drawn from primary documents, company announcements and named trade reporting published between 16 July and 22 August 2026, unless dated otherwise.
The Regulatory Ledger
Dubai, Law No. 4 of 2026
Gulf News, “Revealed: when Dubai’s shared housing law with fines of up to Dh1 million takes effect,” August 2026. Dubai Municipality confirmed the 26 August commencement date directly to Gulf News. https://gulfnews.com/uae/revealed-when-dubais-shared-housing-law-with-fines-of-up-to-dh1-million-takes-effect-1.500628576
Expat Media, “Dubai shared housing law takes effect on August 26,” August 2026. https://www.expatmedia.net/dubai-shared-housing-law-takes-effect-august/2026/08/
Expat Media, “Dubai to launch rental index for shared housing under new law,” August 2026. https://www.expatmedia.net/dubai-rental-index-shared-housing/2026/08/
Binayah, “Dubai to Introduce Rental Index for Shared Housing Units Under New Law,” August 2026, summarising LexisNexis Middle East Practical Guidance on the law. https://www.binayah.com/dubai-to-introduce-rental-index-for-shared-housing-units-under-new-law/
Al Suwaidi & Company, “Law No. 4 of 2026: A New Regulatory Framework for Shared Housing in Dubai.” https://alsuwaidi.ae/law-no-4-of-2026-a-new-regulatory-framework-for-shared-housing-in-dubai/
Shuaib Alsuwaidi Advocates, “Dubai Shared Housing Law 2026: Rules, Fines and Deadline,” updated August 2026. https://advocatealsuwaidi.com/blogs/dubai-shared-housing-law-2026.html
ABS Partners, “Dubai Issues Law No. (4) of 2026 on Shared Housing: What Owners, Tenants and Operators Need to Know.” https://abspartners.ae/dubai-shared-housing-law-2026-owners-tenants/
SAT & Co., “Law No. (4) of 2026: Redefining Shared Housing in Dubai’s Real Estate Market.” https://sat-law.com/law-no-4-of-2026-redefining-shared-housing-in-dubais-real-estate-market/
Real Brief, “Dubai’s Coliving Law Is Official,” June 2026. Source for the point that the numeric occupancy caps, floor-area minimums and fee schedule are delegated to secondary instruments that had not yet published. Link
Saudi Arabia, collective worker housing
Saudi Press Agency, ministry statement on the new regulatory framework and licensing for collective housing, 19 August 2026. https://www.urdupoint.com/arabic/story/2239558.html
Construction Week Online, “Saudi ministry launches initiative to enhance housing for expat workers,” March 2026. Background on the National Program for the Development of Collective Housing. https://www.constructionweekonline.com/news/saudi-ministry-housing-expat-workers
London, Draft London Plan
Savills, “Does the Draft London Plan truly recognise the value and viability of co-living in London?”, August 2026. Source for the removal of Policy H16, dispersal into HN3, HN5 and HN9, the roughly 85% fall in starts from the Q4 2023 peak, and just over 16,000 consented units not started as of July 2026. https://www.savills.co.uk/blog/article/393456/commercial-property/does-the-draft-london-plan-truly-recognise-the-value-and-viability-of-co-living-in-london-.aspx
Savills, “Savills provides initial thoughts on new draft London Plan,” July 2026. Source for HN5 combining PBSA and large-scale purpose-built shared living into one Managing Specialist Accommodation policy, and for borough PBSA targets totalling 31,549. https://www.savills.co.uk/insight-and-opinion/savills-news/392980/savills-provides-initial-thoughts-on-new-draft-london-plan
Greater London Authority, Large-scale Purpose-built Shared Living London Plan Guidance, for the existing Policy H16 framework being replaced. https://www.london.gov.uk/programmes-strategies/planning/implementing-london-plan/london-plan-guidance/large-scale-purpose-built-shared-living-lpg
Property Week, “Shared future: prospects for the co-living sector,” 28 July 2026. Regional viability and investor hesitancy outside London. https://www.propertyweek.com/markets/shared-future
United States, occupancy reform
HousingWire, Richard Lawson, “More states legalize co-living; PadSplit adds insurance for hosts,” 4 August 2026. Primary source for the state-by-state position, the National Co-Living Association, and Sam Hooper’s comments. https://www.housingwire.com/articles/more-states-legalize-co-living-padsplit-adds-insurance-for-hosts/
The Money Moved Twice
Bain Capital, “Meridia Acquires a Landmark Flex Living Asset in Madrid from Bain Capital-led Consortium,” 6 August 2026. https://www.baincapital.com/news/meridia-acquires-landmark-flex-living-asset-madrid-bain-capital-led-consortium
BDC Magazine, “DFI forward funds 200-bed Kingston co-living development in off-market transaction,” August 2026. Also the source for approximately 7,000 operational co-living beds across London. https://bdcmagazine.com/2026/08/dfi-forward-funds-200-bed-kingston-co-living-development-in-off-market-transaction/
Green Street News, “DFI adds 200 homes to co-living portfolio,” 19 August 2026. https://greenstreetnews.com/article/dfi-adds-200-homes-to-co-living-portfolio/
Global Student Living, “London Office Plan Revised to Include 530 Co-Living Homes,” 3 August 2026, summarising Construction Enquirer. https://gslglobal.com/2026/08/03/london-office-plan-revised-to-include-530-co-living-homes/
Global Student Living, “Lendlease Submits Final Proposal for 2,000-Home Stratford Development,” 21 August 2026. https://gslglobal.com/2026/08/21/lendlease-submits-final-proposal-for-2000-home-stratford-development/
The Habyt Tell
Habyt press page and destinations menu, accessed 22 August 2026. Source for the sequence of announcements: Mitsubishi Estate acquiring Asia Pacific operations (April 2026), the sale of French, Portuguese and Spanish co-living portfolios to three local operators (May 2026), the Atipico hotel brand, and the Leaze launch (May 2026). https://habyt.com/press
Serviced Apartment News, “Habyt to open 319-unit Vienna aparthotel in August,” June 2026. https://servicedapartmentnews.com/news/habyt-319-unit-aparthotel-austria-august/
ImmoFokus, “Soft Opening für Habyt Vienna,” August 2026. https://immofokus.at/a/soft-opening-fuer-habyt-vienna
Asset Physics, “Soft Opening for Habyt Vienna,” August 2026. https://assetphysics.com/soft-opening-for-habyt-vienna/
The PadSplit Arithmetic
PadSplit via PRWeb, “PadSplit launches HostGuard: the first-ever protection plan designed for shared housing,” 5 August 2026. https://www.prweb.com/releases/padsplit-launches-hostguard-the-first-ever-protection-plan-designed-for-shared-housing-302843770.html
PadSplit via PRWeb, “PadSplit Named to Inc. 5000 List for Fifth Consecutive Year,” 11 August 2026. https://www.prweb.com/releases/padsplit-named-to-inc-5000-list-for-fifth-consecutive-year-302846755.html
HousingWire, Richard Lawson, 4 August 2026, as above. Source for the 2.25% transaction fee increase, the roughly $4 a week figure, Atticus LeBlanc’s AirCover comparison and his comments on rejection rates, and the 85,000 people housed across more than 35,000 rooms. https://www.housingwire.com/articles/more-states-legalize-co-living-padsplit-adds-insurance-for-hosts/
Everything Coliving, “PadSplit and the American Coliving Paradox,” March 2026. My prior published position on the definitional question, and the median tenant income figure. https://everythingcoliving.substack.com/p/padsplit-and-the-american-coliving
Singapore
Global Student Living, “Singapore Launches Pilot Co-Living Program for Youth,” 20 August 2026. https://gslglobal.com/2026/08/20/singapore-launches-pilot-co-living-program-for-youth/
Grow Beansprout, “LHN Limited: Strong results for 1H2026, boosted by Coliwoo.” Source for Coliwoo at 3,568 rooms across 28 locations and 97.0% occupancy as at 31 March 2026. https://growbeansprout.com/lhn-1hfy26-results
TipRanks, “LHN Leans on High-Occupancy Co-Living and New Contracts to Drive 1H 2026 Growth.” https://www.tipranks.com/news/company-announcements/lhn-leans-on-high-occupancy-co-living-and-new-contracts-to-drive-1h-2026-growth
Everything Coliving, State of Coliving hub, for the Singapore regulatory position: 90-day minimum stays, occupancy caps and Service Apartment classification. https://www.everythingcoliving.com/state-of-coliving
The Watchlist
Urban Living News, webinar listing, “The future of coliving,” 11 September 2026.
https://urbanliving.news/
Background reading that shaped the analysis but is not quoted
INTRIC Research, “Co-Living in 2026: Proven Demand, Fragile Operations, and a Premium That Vanishes Net of Cost,” July 2026. Particularly useful on the point that JLL’s EMEA living data contains no standalone co-living volume or yield series, so the institutionalisation of “living” is not evidence of the institutionalisation of coliving. https://intricglobal.com/en/insights/articles/co-living-flexible-living-2026
Lichfields, “2025: the year co-living came of age,” January 2026. https://lichfields.uk/blog/2026/january/23/2025-the-year-co-living-came-of-age
Knight Frank Australia, The Co-Living Report, January 2026. https://www.knightfrank.com.au/blog/2026/01/19/development-of-coliving-units-expected-to-accelerate-in-2026
Colliers India, “Co-living segment gains traction in India; inventory to reach approximately 1 million beds by 2030,” May 2025. https://www.colliers.com/en-in/news/press-release-coliving-segment-in-india
Everything Coliving, State of Coliving 2026 and Coliving Statistics 2026, for the comparative country and market-size baselines used throughout. https://www.everythingcoliving.com/state-of-coliving https://www.everythingcoliving.com/coliving-statistics