


In the same week that Goldman Sachs completed its acquisition of Urban Campus, The Collective, once the poster child of European coliving, officially collapsed after failing to find a buyer. Meanwhile, Barcelona’s coliving-managed properties have surged 900% in five years, triggering mass protests, and London just greenlit over 2,000 new co-living units across multiple schemes.
If you’ve been watching this industry for a while, this shouldn’t surprise you. But the speed at which all of this is happening in a single two-week window? That’s new.
In this edition, we cover:
[Deep Dive] Goldman Sachs Acquires Urban Campus: What this means for institutional capital in coliving
[Industry News] The Collective Collapses: The end of an era, and lessons for the rest of us
[Market Analysis] Barcelona’s 900% Coliving Surge: Protests, regulation, and the fight for housing rights
[Pipeline Update] London’s Co-Living Boom: 46-storey towers, £200M capital raises, and 2,000+ new units
[Global Round-Up] Everything Else in Coliving: Brisbane, Singapore, Fukuoka, Oakland, India, and more
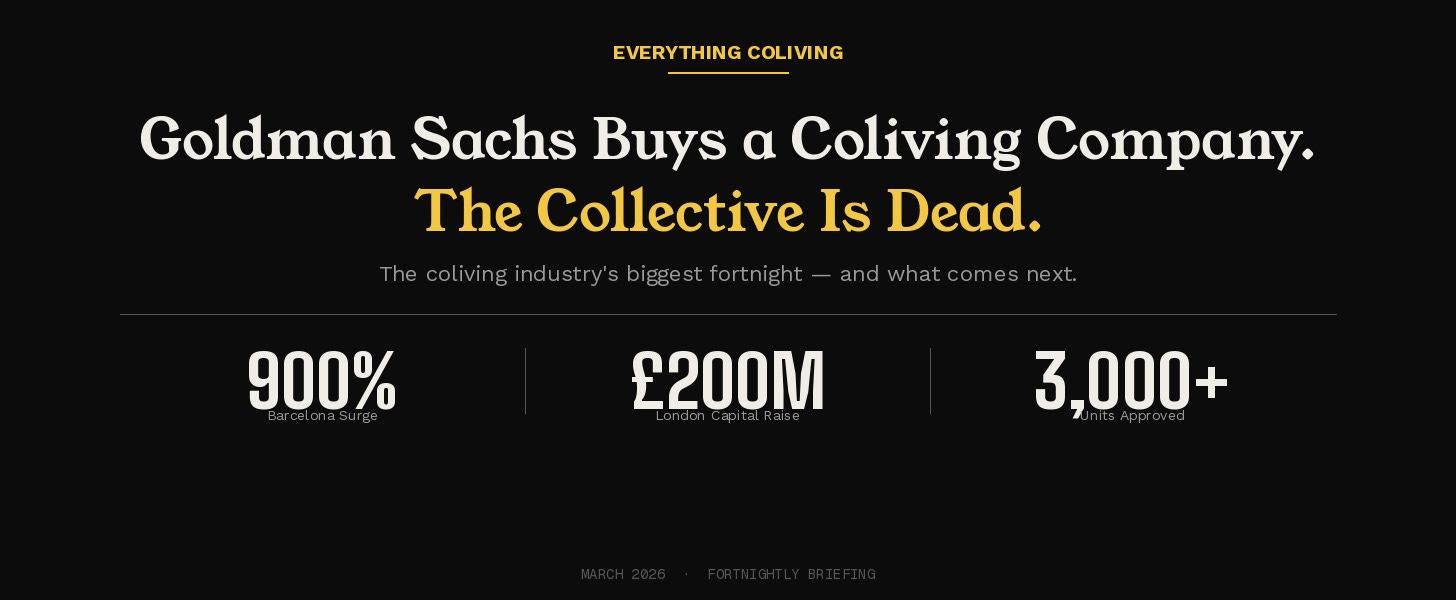
[Deep Dive] Goldman Sachs Has Completed the Acquisition of Urban Campus. Let That Sink In.
This is the story of the fortnight. Goldman Sachs has completed its acquisition of Urban Campus, the Madrid-headquartered coliving and build-to-rent operator. CoStar broke the news on March 12, and the implications are enormous.
Here’s why this matters more than any single funding round or project launch we’ve covered in recent memory.
Urban Campus isn’t a startup chasing scale. It’s an operator with real assets, real operations, and a real track record across European markets. For Goldman Sachs, one of the most sophisticated institutional investors on the planet, to not just invest but acquire a coliving operator outright signals something profound: coliving has crossed the threshold from “alternative asset experiment” to “institutional asset class.”
Let me be direct. We’ve seen capital enter the coliving space before. We’ve seen venture rounds, we’ve seen PE backing, we’ve seen JVs. But an outright acquisition by Goldman Sachs? This is a different conversation entirely. This says: the economics work, the model is scalable, and the risk-adjusted returns justify a permanent capital allocation.
For operators reading this, here’s the takeaway: institutional capital doesn’t just validate your business model, it changes the competitive landscape. The operators who will thrive in this next phase are the ones with disciplined unit economics, clean data, and operational systems that can survive institutional-grade due diligence. If your P&L can’t withstand a Goldman analyst picking it apart, you’re not ready for what’s coming.
And for the broader industry? This acquisition will accelerate the institutionalisation of coliving globally. Expect more acquisitions, more consolidation, and more capital flowing into operators who can demonstrate repeatable, scalable performance.
[Industry News] The Collective Is Dead. Here’s What the Industry Should Learn.
In the same week, The Collective, once the darling of European co-living, has officially collapsed. Crain’s New York Business and Hoodline both reported that the firm failed to find a buyer, and its Brooklyn and Queens ambitions have stalled permanently.
I want to handle this with the nuance it deserves, because The Collective mattered. It was one of the first operators to prove that coliving could exist at institutional scale. Its Old Oak development in London was, at the time, the largest co-living building in the world. It pushed the design conversation forward. It attracted serious capital. It expanded internationally.
But here’s what went wrong, and it’s a lesson every operator in this industry needs to internalise:
Scaling ahead of unit economics. The Collective raised enormous capital and expanded into multiple markets, London and New York, before proving that its per-unit economics were sustainable. The buildings were stunning, but the cost to deliver and operate them outstripped the revenue they could generate.
Premium positioning in a market that rewards affordability. As I’ve written before, the coliving companies that are winning right now, globally, are the ones solving for affordability. PadSplit, Habyt, and even the new wave of European operators. The market increasingly rewards operators who deliver value, not luxury. The Collective bet on the high end, and the market shifted beneath it.
The graveyard of coliving unicorns is long and painful. WeLive, Ollie, Quarters, Common (restructured), and now The Collective. The pattern is consistent: over-raise, over-build, and under-deliver on returns. The survivors are the ones who started small, proved unit economics, and scaled methodically.
The contrast with the Goldman-Urban Campus deal couldn’t be sharper. Goldman didn’t buy the flashiest coliving brand. It bought the one with disciplined operations.
Rest in peace, The Collective. You moved the needle. But the industry has moved on.
[Market Analysis] Barcelona’s Coliving War Escalates: 900% Growth, 1,000+ Protesters, and a City at Breaking Point
Barcelona is becoming the global epicentre of the coliving regulation debate, and the last two weeks have been extraordinary.
Here’s what happened: RAC1 reported that coliving properties managed by companies in Barcelona have increased by 900% in five years. Let that number sit with you. Nine hundred percent. In a city already in the grip of a severe housing affordability crisis.
The response has been immediate and intense. Over 1,000 people gathered in Barcelona to demand housing policy action, with coliving explicitly named as a target. BComerç, the city’s major business association, has demanded that the city government present the urban planning regulation that would prohibit coliving conversions. Betevé reported that unions are pressing to recover 17 coliving rooms in the city. And residents are demanding that Mayor Jaume Collboni enforce existing regulations on coliving conversions.
Why this matters for the global coliving industry: Barcelona is the canary in the coal mine for what happens when coliving growth outpaces regulation and community acceptance. The city isn’t opposed to innovation in housing, it’s opposed to the displacement that unregulated conversion of residential units into short-stay coliving creates.
Here’s what I think is really going on. The problem isn’t coliving itself. The problem is that a segment of operators are converting long-term residential apartments into high-turnover, high-margin coliving units, effectively removing housing stock from the long-term rental market. In a city where rents have been climbing relentlessly, this is politically explosive.
The operators who will survive the regulatory reckoning in Barcelona, and it is coming, are the ones building purpose-built coliving that adds to housing supply rather than converting existing stock. New supply, not conversion. That’s the only defensible model in markets with acute housing shortages.
Meanwhile, the contrast with Madrid is striking. Madrid is actively welcoming coliving and flexible accommodation, with proposals to allow aparthotels and coliving in industrial zones (EL PAÍS, March 5). GMP is launching premium coliving projects in the city. Barcelona’s loss is, once again, Madrid’s gain.
Browse the upcoming coliving events here.

[Pipeline Update] London’s Co-Living Pipeline Just Got Massive
London had a remarkable two weeks. Let me walk you through the numbers:
Olympian Homes: 46-Storey Co-Living Tower at Canary Wharf. Developer Olympian Homes received planning approval for a 46-storey co-living tower at Marsh Wall in Canary Wharf (Property Week, March 4). This will be one of the tallest purpose-built co-living buildings in the UK when completed.
Mastmaker Court: 843 Co-Living Units Approved. Two residential towers delivering 843 co-living apartments and 153 affordable homes were approved on the Isle of Dogs (Wharf Life, March 14). Near-1,000 homes in a single scheme.
Re:shape Seeks £200M for London Co-Living. Developer Re:shape is seeking £200M in institutional joint venture equity for 1,554 co-living assets in London (BE News, March 10). They also received planning permission for a 386-home riverside co-living development in Salford; the city’s third approved co-living scheme (Estates Gazette, March 6).
Former GlaxoSmithKline HQ: 1,500+ Homes. A brownfield site in West London will be regenerated with over 1,500 homes, including student flats and co-living space (Housing Today, March 11).
Woolwich: 156 Co-Living Homes. The Poundstretcher store in Woolwich received the green light for replacement with 156 co-living homes (The Greenwich Wire, March 2).
Add it all up and we’re looking at well over 3,000 co-living units approved or in advanced pipeline across London and Salford in just two weeks. The UK coliving sector is scaling rapidly, and the development community clearly sees long-term demand.
What’s notable is the diversity of developers. This isn’t one company building everything; it’s Olympian, Re:shape, and multiple other developers all independently pursuing coliving at scale. That’s a market signal, not a single bet.
[Global Round-Up] Everything Else in Coliving
Australia: Arklife Doubles Down on Brisbane. Arklife is extending into Australia’s co-living sector with plans in Brisbane (The Urban Developer, March 5), and a new 15-storey, 312-room co-living development has been proposed for Fortitude Valley (Brisbane Times, March 16). Australia’s co-living market is quietly building momentum.
Singapore: Coliwoo Eyes $218.5M Asset Sale. LHN Group’s co-living spinoff Coliwoo is seeking to sell 7 freehold assets for S$218.5 million (The Business Times, March 6). Meanwhile, Coliwoo’s new Midtown Singapore project features wellness amenities including ice baths and chef dinners (Stacked Homes, March 6). The Assembly Place has signed a JV for migrant workers’ accommodation — an interesting adjacency for coliving operators to watch.
Japan: Colive Fukuoka Wins Best Global Nomad Fest Award. During its pop-up coliving programme in October 2025, Colive Fukuoka welcomed 496 participants from 57 countries (Lincoln Journal, March 15). This is what community-first coliving looks like at its best.
Oakland, USA: Radish Is Being Uprooted. The San Francisco Standard reported that Radish, Oakland’s beloved grassroots co-living compound, is up for sale at $4-6M (March 8). A reminder that not all coliving is institutional, and the grassroots community models face their own existential pressures.
India: Coliving as the Answer to Urban Loneliness. The Hans India reported on the growing popularity of co-living spaces addressing social isolation among young professionals in Indian cities (March 8). This is the narrative that will drive demand growth in emerging markets, not just beds, but belonging.
Investor Sentiment, Savills Confirms the Trend. Savills’ latest investor survey found rising interest in single family, coliving, senior living, and care homes (March 10-11). Student accommodation and coliving are trending in institutional investment portfolios. This aligns perfectly with the Goldman-Urban Campus story, capital is flowing into the sector at an accelerating pace.
Spain: The Tale of Two Cities Continues. While Barcelona fights coliving, smaller Spanish cities are embracing it. Ponferrada opened coliving in its historic centre (Info Bierzo, March 14). Pas Rural launched a coliving-coworking space in rural Cantabria. Crowdfunding platform Urbanitae is launching a coliving project in Bouzas. The decentralisation thesis for coliving in Spain is playing out in real time.
UK Regional: Salford Becomes a Co-Living Hub. With three co-living schemes now approved, Salford is emerging as a secondary co-living hub outside London. Re:shape’s 386-home riverside development, approved by Salford City Council with a 24-storey Buttress-designed tower, signals that co-living is no longer a London-only story in the UK.
Final Thoughts
This fortnight crystallised something I’ve been saying for a while: the coliving industry is bifurcating. On one side, you have institutional capital arriving in force: Goldman Sachs, Re:shape’s £200M raise, and Savills confirming investor appetite. On the other, you have operators who over-leveraged, under-delivered, or grew without community buy-in paying the price: The Collective’s collapse, Barcelona’s backlash, and Oakland’s Radish facing the market.
The operators who will define the next decade of coliving are the ones who can hold both truths simultaneously: deliver institutional-grade returns and genuine community value. Add to the housing supply rather than convert it. Scale operations without sacrificing the human element that makes coliving coliving.
The capital is here. The demand is here. The question now is execution.
Until next time,
Mayank Pokharna Everything Coliving
That’s it for this edition. If you found value in this newsletter, share it with someone building, operating, or investing in coliving. And if you’re working on something interesting in the space, a project, a deal, a new market, hit reply. We love hearing from the frontlines.
Your description that Radish in Oakland has failed is inaccurate. Radish organizers always planned to sell their property after 10 years in order to guarantee their investors could cash out, and because they assumed they would want bigger places when they had more, older children. All of the residents are moving on to other friend compounds. It will continue to be a friend compound with other owners and residents. The industrialization and financialization of collective living is what leads to failure from the point of view of residents.
Goldman Sachs won't care if their properties no longer exist as co-living in 5-10 years. They will have sucked as much profit as possible out of them.