


If you missed the last two editions, here they are.


In this edition:
[Opinion] The Two Faces of Coliving in 2026: Record Towers and Street Protests
[Deep Dive] Barcelona’s Coliving War: 1,100 Protestors, 44 Fraud Complaints, and a Ban on the Horizon
[Market Analysis] Bisnow: Coliving Developers Are Finding Funders, But Profits Are on the Back End
[Market News] Madrid’s Flex Living Boom: GMP’s 724-Unit Bet and Gaiastays’ Rapid Expansion
and Everything Else Coliving
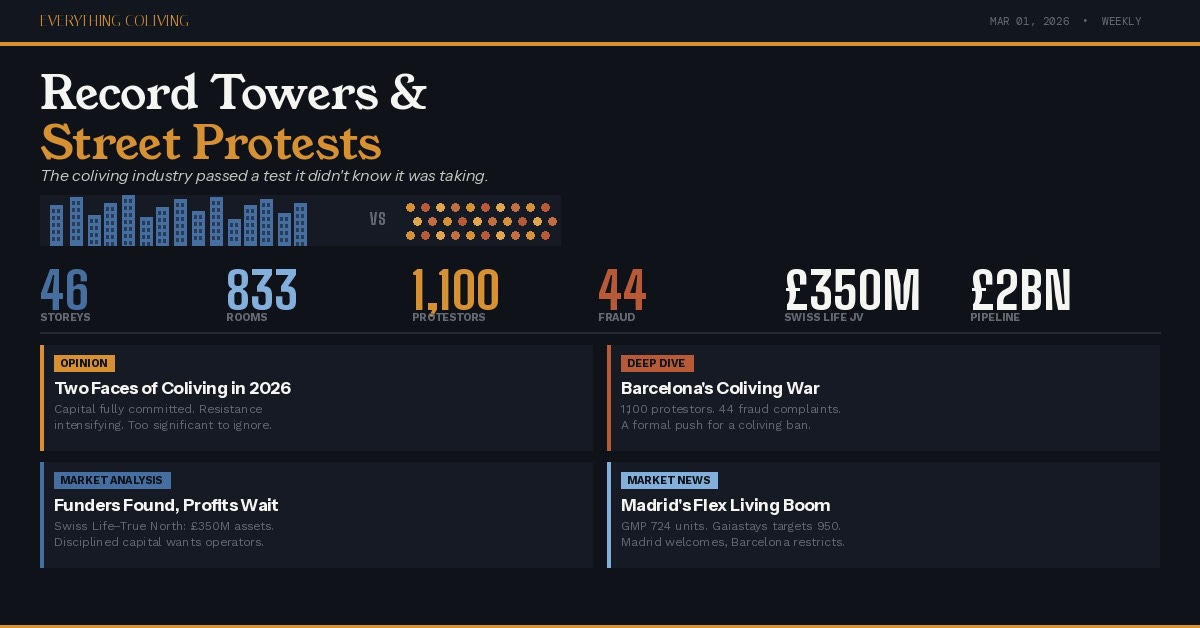
[Opinion] The Two Faces of Coliving in 2026: Record Towers and Street Protests
In the same week, two things happened that perfectly capture where the coliving industry stands right now.
In London, Olympian Homes cleared Gateway 2 approval for the UK’s tallest co-living scheme, a 46-story tower at 56 Marsh Wall in Canary Wharf with 833 studio rooms. The Rio Architects-designed tower will feature hotel-style amenities: 24-hour concierge, cinema, gym, and winter garden. Olympian’s Vivus Living brand is targeting a £2 billion pipeline. This isn’t a niche operator testing the waters. This is a company building a portfolio on the premise that co-living is the future of urban housing at an institutional scale.
In Barcelona, more than 1,100 people gathered at Plaza Sant Jaume demanding the city take action against coliving. The slogan: “Prou excuses: els pisos per viure-hi,” or “No more excuses: apartments are for living in.” Not for rotating tenants. Not for investment vehicles. For living.
Two cities. Same week. Same industry. Completely different stories.
And yet, both stories are telling us the same thing: coliving has become too significant to ignore.
The 46-story tower tells us that institutional capital has fully committed. You don’t design an 833-room building on a Canary Wharf site without serious underwriting, serious demand modeling, and serious conviction that this asset class has legs. When the Building Safety Regulator signs off on the UK’s tallest co-living scheme, the regulatory machinery is accommodating the model, not resisting it.
The 1,100 protestors tell us that the social contract around coliving hasn’t been written yet. Housing unions in Barcelona aren’t protesting a concept. They’re protesting a reality: buildings converted without community consent, rooms advertised at prices that violate rent caps, permanent residents displaced by rotating tenants.
The industry can’t choose one narrative and ignore the other. The tower and the protest are connected. Capital flows because demand is real. Protests happen because supply conversion without guardrails creates losers. The operators who understand both forces, who can build at the scale of Olympian while respecting communities like Barcelona’s housing unions demand, will define the next decade.
The ones who only see the tower will eventually face the protestors. And the ones who only see the protests will miss the biggest asset class opportunity in a generation.
Consider the numbers. In the past two weeks alone:
46 storeys and 833 rooms approved in London’s Canary Wharf
£350 million in co-living assets under management by a single Swiss Life JV
724 premium coliving units launched by GMP in Madrid
656 student beds approved in Sydney
1,500 homes (including co-living) greenlit in Woolwich
250+ flex living assets under Gaiastays, targeting 950 by 2027
And on the other side:
1,100 protestors in Barcelona demanding coliving restrictions
44 fraud complaints filed against coliving operators in Catalonia
A formal push for a coliving ban in Barcelona’s planning code
Tenants pushed out in France to make way for “new generation” coliving (Capital magazine)
This is the moment. Not a future state. Not a five-year projection. Right now, the industry is simultaneously reaching institutional maturity and facing its most serious social resistance.
This week’s news makes the duality impossible to avoid. Let’s dig into both sides.
[Deep Dive] Barcelona’s Coliving War: 1,100 Protestors, 44 Fraud Complaints, and a Ban on the Horizon
Barcelona’s coliving conflict went from simmering to boiling this week. Three developments, each escalating beyond what we saw even two weeks ago.
The protest. On February 28, over 1,100 people rallied at Plaza Sant Jaume, Barcelona’s political nerve centre, demanding effective housing policies. Housing unions explicitly targeted coliving alongside seasonal rentals as practices that are hollowing out residential neighbourhoods. The demonstration was organised under the banner of the right to housing, but coliving was a named villain.
The fraud complaints. Housing advocacy groups filed formal complaints with Catalan consumer protection agencies documenting 44 coliving listings that violate rental price regulations. Companies were advertising rooms at €900–950 per month in areas where regulations cap prices far lower. The complaints allege systematic exploitation of regulatory loopholes, operators marketing what are essentially rental rooms as “coliving experiences” to dodge price controls. This is the part that should worry every legitimate operator. When 44 listings in one city are flagged as potentially fraudulent, it’s not an isolated bad actor. It’s a pattern. And patterns attract regulation.
The ban. Barcelona en Comú (BComú) is now pushing the city to adopt a planning regulation that would explicitly prohibit colivings and seasonal rentals. The proposed modification would define housing strictly for permanent habitation, effectively making the coliving business model illegal within city limits. BComú has extracted a commitment from the governing coalition to present this norm.
Let me be direct: a coliving ban in Barcelona would be the most significant regulatory action against the industry in Europe to date. Paris has pushed back against individual projects. France refused to create a legal framework. But an outright prohibition through planning law? That’s a different order of magnitude.
What the industry needs to understand:
Barcelona isn’t happening in a vacuum. It’s the leading indicator for every European city where coliving is growing fast. The sequence is predictable: rapid growth → displacement stories → consumer complaints → political mobilisation → regulatory response. We saw it in Paris. We’re seeing it in Lyon. Barcelona is simply further along the curve.
The question isn’t whether other cities will follow. It’s whether the industry can change the trajectory before they do. And that means:
Price transparency. If operators are charging above regulated caps by calling it “coliving” instead of “rental,” they’re poisoning the well for everyone.
Community integration. Operators need to be visible, accountable community members, not anonymous building converters.
Industry self-governance. If we don’t police the 44 bad listings, regulators will police all of us.
Barcelona offered €30,000 in grants this week to rehabilitate social rental housing. That’s the city signalling where its priorities lie. Coliving operators who can align with those priorities, not against them, still have a path. But the window is closing.
There’s an important lesson here for the global industry. Barcelona’s problems aren’t unique to Barcelona. They’re the predictable result of a specific failure: the failure to distinguish between coliving that adds housing supply and coliving that converts existing housing. The former solves problems. The latter creates them. Every operator, investor, and policymaker needs to be crystal clear about which side of that line they’re on.
The 44 fraud complaints are particularly damaging because they suggest some operators aren’t just on the wrong side of the line; they’re actively exploiting the ambiguity. When rooms are advertised at €900+ in areas where price caps exist, that’s not a grey area. That’s a business model built on regulatory arbitrage. And regulatory arbitrage has a shelf life. When it expires, it takes legitimate operators down with it.
[Market Analysis] Coliving Developers Are Finding Funders, But Profits Are on the Back End
Bisnow published one of the most important coliving industry analyses this week, and the headline tells you everything: developers are finding funders, but they may have to wait for profits.
The key data point: a Swiss Life–True North Management joint venture now manages seven co-living schemes worth approximately £350 million. That’s institutional capital at scale, a Swiss insurance giant backing coliving as a long-term asset play.
But the Bisnow analysis reveals the tension at the heart of the current funding landscape:
Capital is available. Lenders are comfortable with the asset class. Development finance is flowing (as we covered last week with £25m+ in UK loans).
Returns are back-ended. Unlike traditional residential, coliving’s economics reward patient capital. Stabilisation takes longer. Operational complexity is higher. The yield curve is real but slower.
Investors want best-in-class. The funding isn’t indiscriminate. Investors are seeking proven operators, strong locations, and differentiated product. The era of “any coliving scheme gets funded” is over before it began.
Why this matters for operators:
If you’re raising capital for a coliving development, the message is clear: the money exists, but it’s disciplined money. You need to demonstrate operational capability, not just a development pipeline. The Swiss Life model, pairing institutional capital with an experienced operator (True North), is likely the template for how the industry scales from here. Insurance companies and pension funds think in decades, not development cycles. They want recurring income from well-managed assets, which is exactly what best-in-class coliving delivers.
This also explains why we’re seeing so much consolidation activity. Estates Gazette reported on the shift “from place-making to place-keeping”, arguing that sustainable returns in the living sector come from long-term stewardship, not just development. That’s the investor mindset now: build it, operate it excellently, and the returns compound over time.
The practical takeaway for founders and operators: If your pitch deck focuses on development margins, you’re speaking the wrong language. Institutional investors want to see occupancy stabilisation timelines, operational cost ratios, resident satisfaction metrics, and churn rates. The coliving operators who can demonstrate operational excellence will attract capital. The ones who can only demonstrate a construction permit will find the well drying up.
Connect this to the Olympian story: an 833-room tower isn’t just a development bet, it’s an operational bet. Running a 46-storey building with hotel-style amenities for 833 residents requires a fundamentally different skill set than developing it. The operators who crack that operational code at scale will define the next chapter of this industry.
[Market News] Madrid’s Flex Living Boom: GMP’s 724-Unit Bet and Gaiastays’ Rapid Expansion
Madrid is emerging as Europe’s most dynamic coliving expansion market, and this week’s news reinforces why.
GMP launches Truliving with 724 units across three Madrid projects. The traditionally office-focused developer launched its Truliving brand with premium coliving developments in Sanchinarro, Valdebebas, and Alcobendas. Construction for two projects (approximately 300 and 400+ homes) is imminent. When a developer of GMP’s pedigree, known for prime office and business parks, pivots to coliving, it tells you where the smart money sees the growth.
Gaiastays surpasses 250 assets, targets 950 by 2027. The flex living operator added three Madrid properties (Santa Valentina, Hortaleza Lofts, Retiro I) and now plans to double to 450 units by end of 2026 and reach 950 by 2027. Expansion is planned for Granada, Valencia, Bilbao, and A Coruña.
Hestia Inversión Patrimonial appointed a new commercial director to drive expansion of its tourist real estate portfolio, aiming to add 1,300 rooms over five years.
Why Madrid and not Barcelona? The contrast is striking. While Barcelona debates bans, Madrid is welcoming coliving investment. The regulatory environment is more permissive, the development pipeline is accelerating, and institutional operators are choosing Madrid precisely because the political risk is lower. Barcelona’s loss is Madrid’s gain, and this isn’t speculation. It’s visible in the investment flows.
GMP’s decision to launch Truliving in Madrid, not Barcelona, not Valencia, is a deliberate choice. These are premium developments (Sanchinarro, Valdebebas, Alcobendas) in well-connected commuter zones with strong demand fundamentals. The 724-unit commitment tells you GMP isn’t testing the market. They’ve already tested it. They’re scaling.
Gaiastays’ growth trajectory is equally telling. From 250 to 950 assets in under two years would represent nearly 4x growth. The expansion cities, Granada, Valencia, Bilbao, A Coruña, are all secondary markets where housing demand is growing but supply remains constrained. This is the playbook: establish in Madrid, then fan out to cities where the coliving model can address real affordability gaps rather than premium lifestyle positioning.
For the broader industry, Spain is now two case studies in one country. Barcelona shows what happens when coliving grows without community buy-in. Madrid shows what happens when the regulatory environment is permissive and operators are institutional-quality. The operators who study both, and learn from each, will build the most resilient businesses.
Everything Else Coliving
UK Development & Approvals
UK’s tallest co-living tower (46 storeys, 833 rooms) clears Gateway 2 at Canary Wharf. Olympian’s Vivus Living brand targets a £2bn pipeline. Rio Architects designed the tower with a 24-hour concierge, cinema, gym, and winter garden. When the Building Safety Regulator signs off on something of this scale, it sends a signal to every developer in the UK. (Construction Enquirer, Estates Gazette, Green Street News)
Bristol co-living scheme submits revised plans, reducing studios by 13 units to comply with the city’s draft Co-Living Supplementary Planning Document. 100 one-bedroom studios with communal kitchens, lounges, gyms, co-working spaces, and outdoor terraces targeting young professionals and key workers. Bristol is one of the first UK cities creating coliving-specific planning guidance, worth watching as a regulatory template. (Insider Media, Green Street News, BENews)
£200m Bristol student and co-living project clears Gateway. 2. Bristol is quietly becoming a UK co-living hub. (Green Street News)
£425m Woolwich scheme approved, nearly 1,500 homes, including a coliving component, in six buildings up to 23 storeys near the Elizabeth line. The 20-year vacant site is finally being activated. (MyLondon, Building)
FOLK sets a new standard for renting and tackling loneliness in London across three locations (Harrow, Battersea, and Earlsfield), with studios plus communal gyms, co-working, and rooftop terraces. Their four-pillar model (connection, convenience, comfort, contribution) is a nice framework for any operator thinking about brand positioning. (London TV)
Australia & Asia-Pacific
Co-living proposal pushes TOD limits at Marrickville, Sydney. The broader Marrickville Timberyards project is backed by The Living Company with a $1.5bn development of 1,188 rental apartments. (The Urban Developer)
Avenor’s 656-bed South Sydney student project approved, a $145.8m development at Kingsford with two towers (14 and 9 storeys), construction to begin in 2026. (The Urban Developer)
France
Capital magazine reports on tenants being pushed out to make way for “new generation colocation”, a deep dive into the displacement dynamics of the French coliving market, exploring the friction between lifestyle promise and housing reality. (Capital)
Coliving continues to be a hot topic in French media, with coverage spanning Paris, Lyon, and now the Alps for remote worker-targeted mountain coliving concepts.
Spain, Beyond Barcelona
Nuria Canivell, dean of Seville’s College of Architects, highlights prefabrication and flexibility as enablers of cohousing and coliving models, visiting a 92-unit wooden rental project with communal spaces. (Cadena SER)
Spain’s alternative financing for housing construction is hitting regulatory barriers. (Diari de Menorca)
North America
‘Co-living’ is catching on in Connecticut, near UConn in Mansfield and Willimantic, with municipal partnerships shaping a measured rollout. The US co-living story is still early innings outside the major metros, Connecticut shows the model is finding its way into college towns and secondary markets. (The Day/PressReader)
Industry Thought Leadership
Estates Gazette: “From place-making to place-keeping”, an argument that the living sector must shift from development-driven approaches to long-term stewardship for sustainable returns. Required reading for operators thinking beyond the construction phase. (Estates Gazette)
Swiss Life–True North JV manages £350m in co-living assets, the institutional co-living management model taking shape. (Bisnow)
Indonesia
BUMN property asset management strategies highlighted as Indonesian state-owned enterprises optimise coliving portfolios. (CNBC Indonesia)
Housing & Affordability Context
71% of French citizens support rent caps (Odoxa/Immo Matin), a number every operator entering the French market should pin to their wall. The political appetite for regulation is strong and growing.
Alternative financing for housing in Spain is hitting regulatory walls, with coliving and senior living described as “success formats in many countries, but banks will never enter” by Spanish lenders. (Diari de Menorca)
Italy’s homeownership dream continues to fade, with co-living and senior housing advancing as alternatives gain mainstream acceptance. (ItaliaOggi)
Cork Council continues its pilot encouraging co-living for like-minded single people on the housing waiting list, one of the few examples globally of a local government proactively deploying coliving as social housing policy. (Irish Examiner, The Echo)
That’s it for this edition. If you found value in this newsletter, share it with someone building, operating, or investing in coliving. And if you’re working on something interesting in the space, a project, a deal, a new market, hit reply. We love hearing from the frontlines.
Until next time, Mayank Pokharna Everything Coliving
